 Muhammad Adam bin Ali
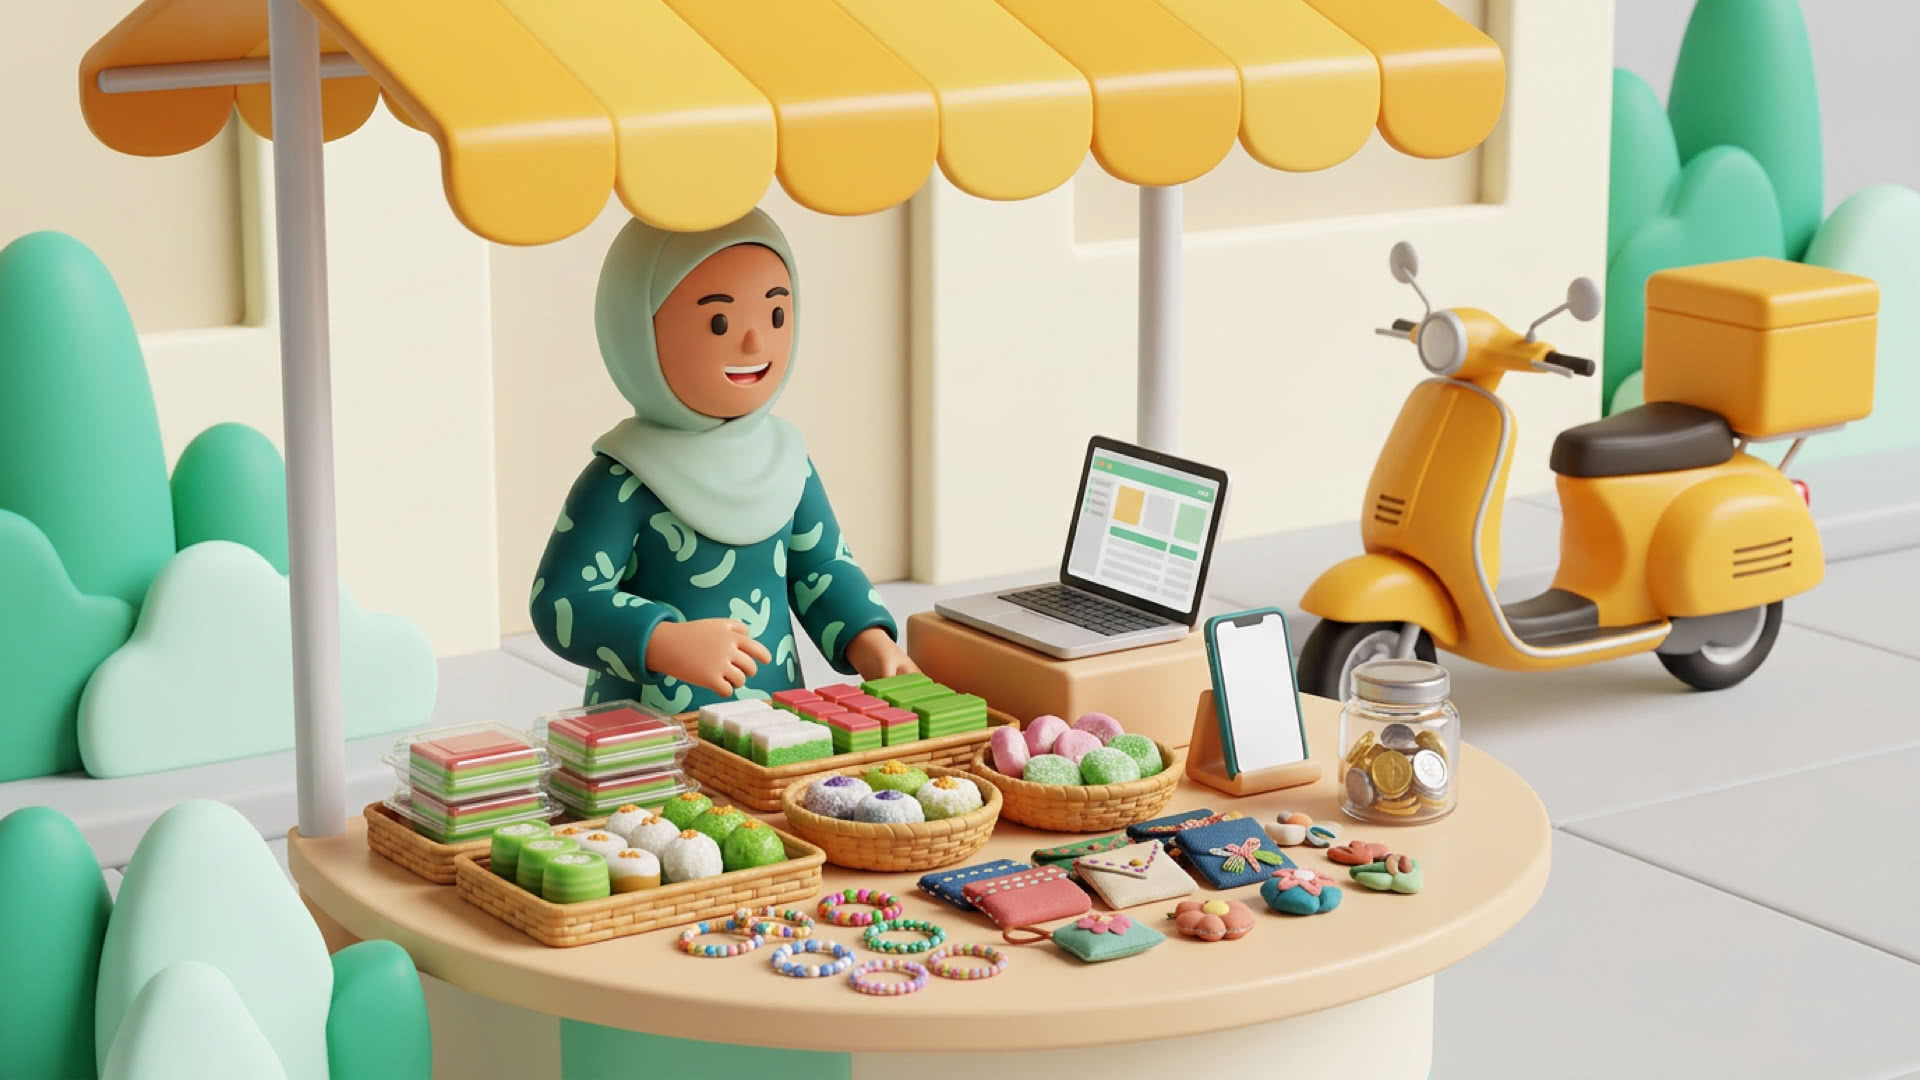
Living costs keep rising and salaries don’t always keep up. A side income can help — if it’s safe and well planned.
Realistic ideas
- Existing skills (tuition, translation, graphic design, video editing, computer repair).
- Gig work (food and parcel delivery, e-hailing).
- Selling online (home-made food, pre-loved items, crafts on e-commerce platforms).
- Local services (house or car cleaning, pet sitting).
Avoid “jobs” that are really scams.
Red flags: paying a deposit or “registration fee”, high pay for very easy tasks, being asked to recruit others, or being asked to lend your bank account. A lent account can be used as a mule account, and you can be investigated by the police.
Manage the extra money well
- Keep side income in a separate account so it’s easy to track.
- Keep records of income and expenses (receipts, platform statements).
- Give it a job: build your emergency fund, clear high-interest debt, or save for the future.
Tax and protection
- Side income generally has to be declared on your annual LHDN tax return — check LHDN’s official guidance or ask a tax agent.
- SOCSO (PERKESO) runs a social security scheme for the self-employed, including gig workers, covering work-related accidents.
- The self-employed can also contribute voluntarily to EPF.
Look after yourself: extra income isn’t worth it if your health or main job suffers. Start with a few hours a week.
Key takeaways
- Use skills you have, avoid work that asks for money or your bank account, keep records and declare your income.
This article is for general education and is not financial advice.

